The future will be funded by solo techno-capitalists
“It’s night in Amsterdam, morning in Silicon Valley. Today, fifty thousand human babies are being born around the world. Meanwhile automated factories in Indonesia and Mexico have produced another quarter of a million motherboards with processors rated at more than ten petaflops—about an order of magnitude below the computational capacity of a human brain. Another fourteen months and the larger part of the cumulative conscious processing power of the human species will be arriving in silicon. And the first meat the new AIs get to know will be the uploaded lobsters.”
Lobsters, by Charles Stross (2001)
In the opening pages of Charles Stross’s Accelerando, Manfred Macx walks through Amsterdam wearing a pair of AR glasses that feed him a constant stream of information — patent filings, academic papers, market data and news feeds.
He doesn’t work for a firm, or manage a fund for LPs. He is a “venture altruist” and “meme-broker”, connecting technologists with capital and ideas for the benefit of his reputation.
Indeed, in a world with autonomous capital, reputation quickly becomes the most valuable resource; Manfred scores about thirty points higher than IBM on the various distributed reputation servers.
“Stross’s game of “What If” is both intense and absurdly optimistic concerning the unstoppable nature of innovation permeating and transforming society. But that’s part of Macx’s character, he pushes these things in places where they’d be most useful, hawking his ideas because he’s a philanthropist who’s abandoned the concept of intellectual property, so he’s purposefully undermining it. In this universe, information wants to be free so badly, a genius can learn to trade ideas as a type of goodwill currency, and it works incredibly well for him.”
Review: Accelerando
Stross wrote Accelerando in 2005, though the introduction (and the character of Macx) were first laid out in his 2001 short story, Lobsters, published in Asimov’s Science Fiction.
Twenty years later, various examples of this “solo techno-capitalist” archetype have proven incredibly successful, reflected across a group of individuals that each own a track record dwarfing any comparable institution.
Cyan Banister, whose superpowers are a childlike curiosity and a keen sense of self, covering everything from cybersecurity to psychedelics and frontier biology.
Peter Thiel, whose investing is built on the philosophy that most VCs are incrementalist cowards, when the real returns are derived from contrarian visions of the future.
Oren Zeev, who manages over $2.5 billion with no office, employees or management fees, making investment decisions within twenty-four hours from a coffee shop in Palo Alto.
Charlie Songhurst, who blended a macro-analyst’s perspective on power structures with an angel investor’s appetite for risk, assembling a portfolio of hundreds of companies.
There is no army of associates or partnership teams required for the investments these people have made independently.
Instead, they rely the ability to consume information, across multiple domains, in high fidelity, and draw more potent conclusions than any committee-led process. And they rely on their reputation, which allows them to cut through noise and process to move more quickly.
“It is with respect to this that practically every individual has some advantage over all others because he possesses unique information of which beneficial use might be made, but of which use can be made only if the decisions depending on it are left to him or are made with his active coöperation.”
The Use of Knowledge in Society, by F. A. Hayek (1945)
They are early avatars of the Macx archetype; solo cognition engines whose performance is derived from irreducible idiosyncracy applied to a vast surface area of possibility.
It’s 2035. A woman in Lisbon wakes up and, before her feet touch the floor, her ambient system has already processed 340 new company filings across seven jurisdictions, cross-referenced against her thesis clusters. Fourteen are flagged as a match. The system knows her blind spots better than she does, because it has been trained on every decision she has made (or not made), and their outcomes, over the past six years.
One is a quantum photonics company in Delft. The system has pulled the founders’ publication histories, patent filings, and a network graph showing their proximity to two researchers whose previous startups she backed in 2026. It has also flagged that the company’s pre-seed round is being led by a manager in Seoul whose portfolio otherwise appears entirely opposed to hers, which she finds interesting. She sends a message. By lunch, she has committed.
She manages an open-ended fund, with no employees. Her LPs include three sovereign wealth funds, a university endowment, and an algorithmic allocation platform that routes capital to managers based on a rolling evaluation of risk-adjusted returns, portfolio distinctiveness, and what the platform’s documentation calls “cognitive alpha,” a proprietary measure of how much a manager’s decision-making diverges from consensus while still generating top-decile outcomes. The platform does not care about her brand, her pedigree, or the size of her team, only the irreducibility of her judgement.
One of the sovereign wealth funds has informed her it will route future allocation through the allocation platform to increase exposure to similar managers, and the others will follow soon after; she has advised them to do so.
This will come to be known as the Macx Threshold.
It is the point at which individual cognition, augmented by AI, becomes a more efficient vehicle for capital allocation than any structure designed to aggregate human judgement.
It’s not that committees are useless, but the function they evolved to perform (reducing variance and ensuring consistency) is precisely the function that destroys alpha.
“We theorize AI as a selective information shock: it can substitute for proximity in codifiable, data-rich activities, but is more likely to complement human judgment, trust, and relational action when ventures are novel, relevant data are sparse.”
Artificial intelligence and venture capital: revisiting sourcing, selection, and nuturing activities (2026)
Venture capital rewards outliers; outliers are best recognised by outlier minds, and outlier minds, by definition, do not survive consensus. The same is true for any pursuit of alpha.
This level of algorithmic allocation, once a thing of science fiction, is an increasingly real proposition. Indeed, the reason institutional capital flows to large funds is not because large funds produce the best returns (the evidence overwhelmingly shows that they do not), but because the operational cost of identifying, underwriting, and monitoring dozens of small managers is prohibitive for a pension fund or sovereign wealth fund that must deploy billions. It’s a decision driven by habit, administrative convenience and venture capital’s lack of courage to challenge that status quo.
“Individuals working with AI showed a substantial 0.37 standard deviation performance increase over the baseline of working alone without AI. This finding suggests that AI can effectively substitute for certain collaborative functions, acting as a genuine teammate by granting individuals access to the varied expertise and perspectives traditionally provided by team members.”
The Cybernetic Teammate: A Field Experiment on Generative AI Reshaping Teamwork and Expertise (2025)
An algorithmic allocation platform that continuously evaluates thousands of small managers against standardised performance metrics, portfolio construction benchmarks, and differentiation scores, eliminates this bottleneck. Capital can flow to the best-performing managers as naturally as it flows to the best-performing stocks in a quantitative equity portfolio. The platform handles the mechanical tasks like capital calls, distributions, compliance and reporting, so the manager can focus on their strength as investors.
“Machine learning tools can use qualitative information to predict future fund performance: the performance spread between the funds within the top and bottom terciles of predicted probability of success is about 25%. Our findings support the view that in opaque and non-standardized markets, investors fail to incorporate qualitative information in their asset manager selection process, but do incorporate salient quantitative information.”
Limited Partners versus Unlimited Machines; Artificial Intelligence and the Performance of Private Equity Funds (2024)
The Macx archetype is the atomic unit of venture capital; a single mind augmented by tools that enhance range, judgement and throughput.
Each manager curates their own view of reality through personalised systems that filter, synthesise, and present information accordingly. One might operate through spatial interfaces that display business relationships and technological convergences. Another might prefer dense textual streams, a descendant of Manfred Macx’s scrolling glasses. A third might work almost entirely through conversation, maintaining an ongoing dialogue with an AI system (perhaps embodied as a robotic feline) that has internalised their philosophy and offers Socratic counterarguments.
Each of these individuals is doing something that a large, consensus-driven organisation cannot, by applying a unique perspective to the challenges of an uncertain future.
For the entire history of venture capital, the connective tissue between institutions and managers has been formed of relationships at an organisational scale. This has structurally favoured incumbents and penalised the new, the small, and the strange. Today, the possibilities of AI have clear benefits to the latter, and pose a real threat to the former.
The future of venture capital is not with the large organisation, which is often just a crude tool to execute lower quality knowledge work at scale.
All such industries are due for a shake-up, and even the investors who have backed this technology aren’t immune from the consequences.
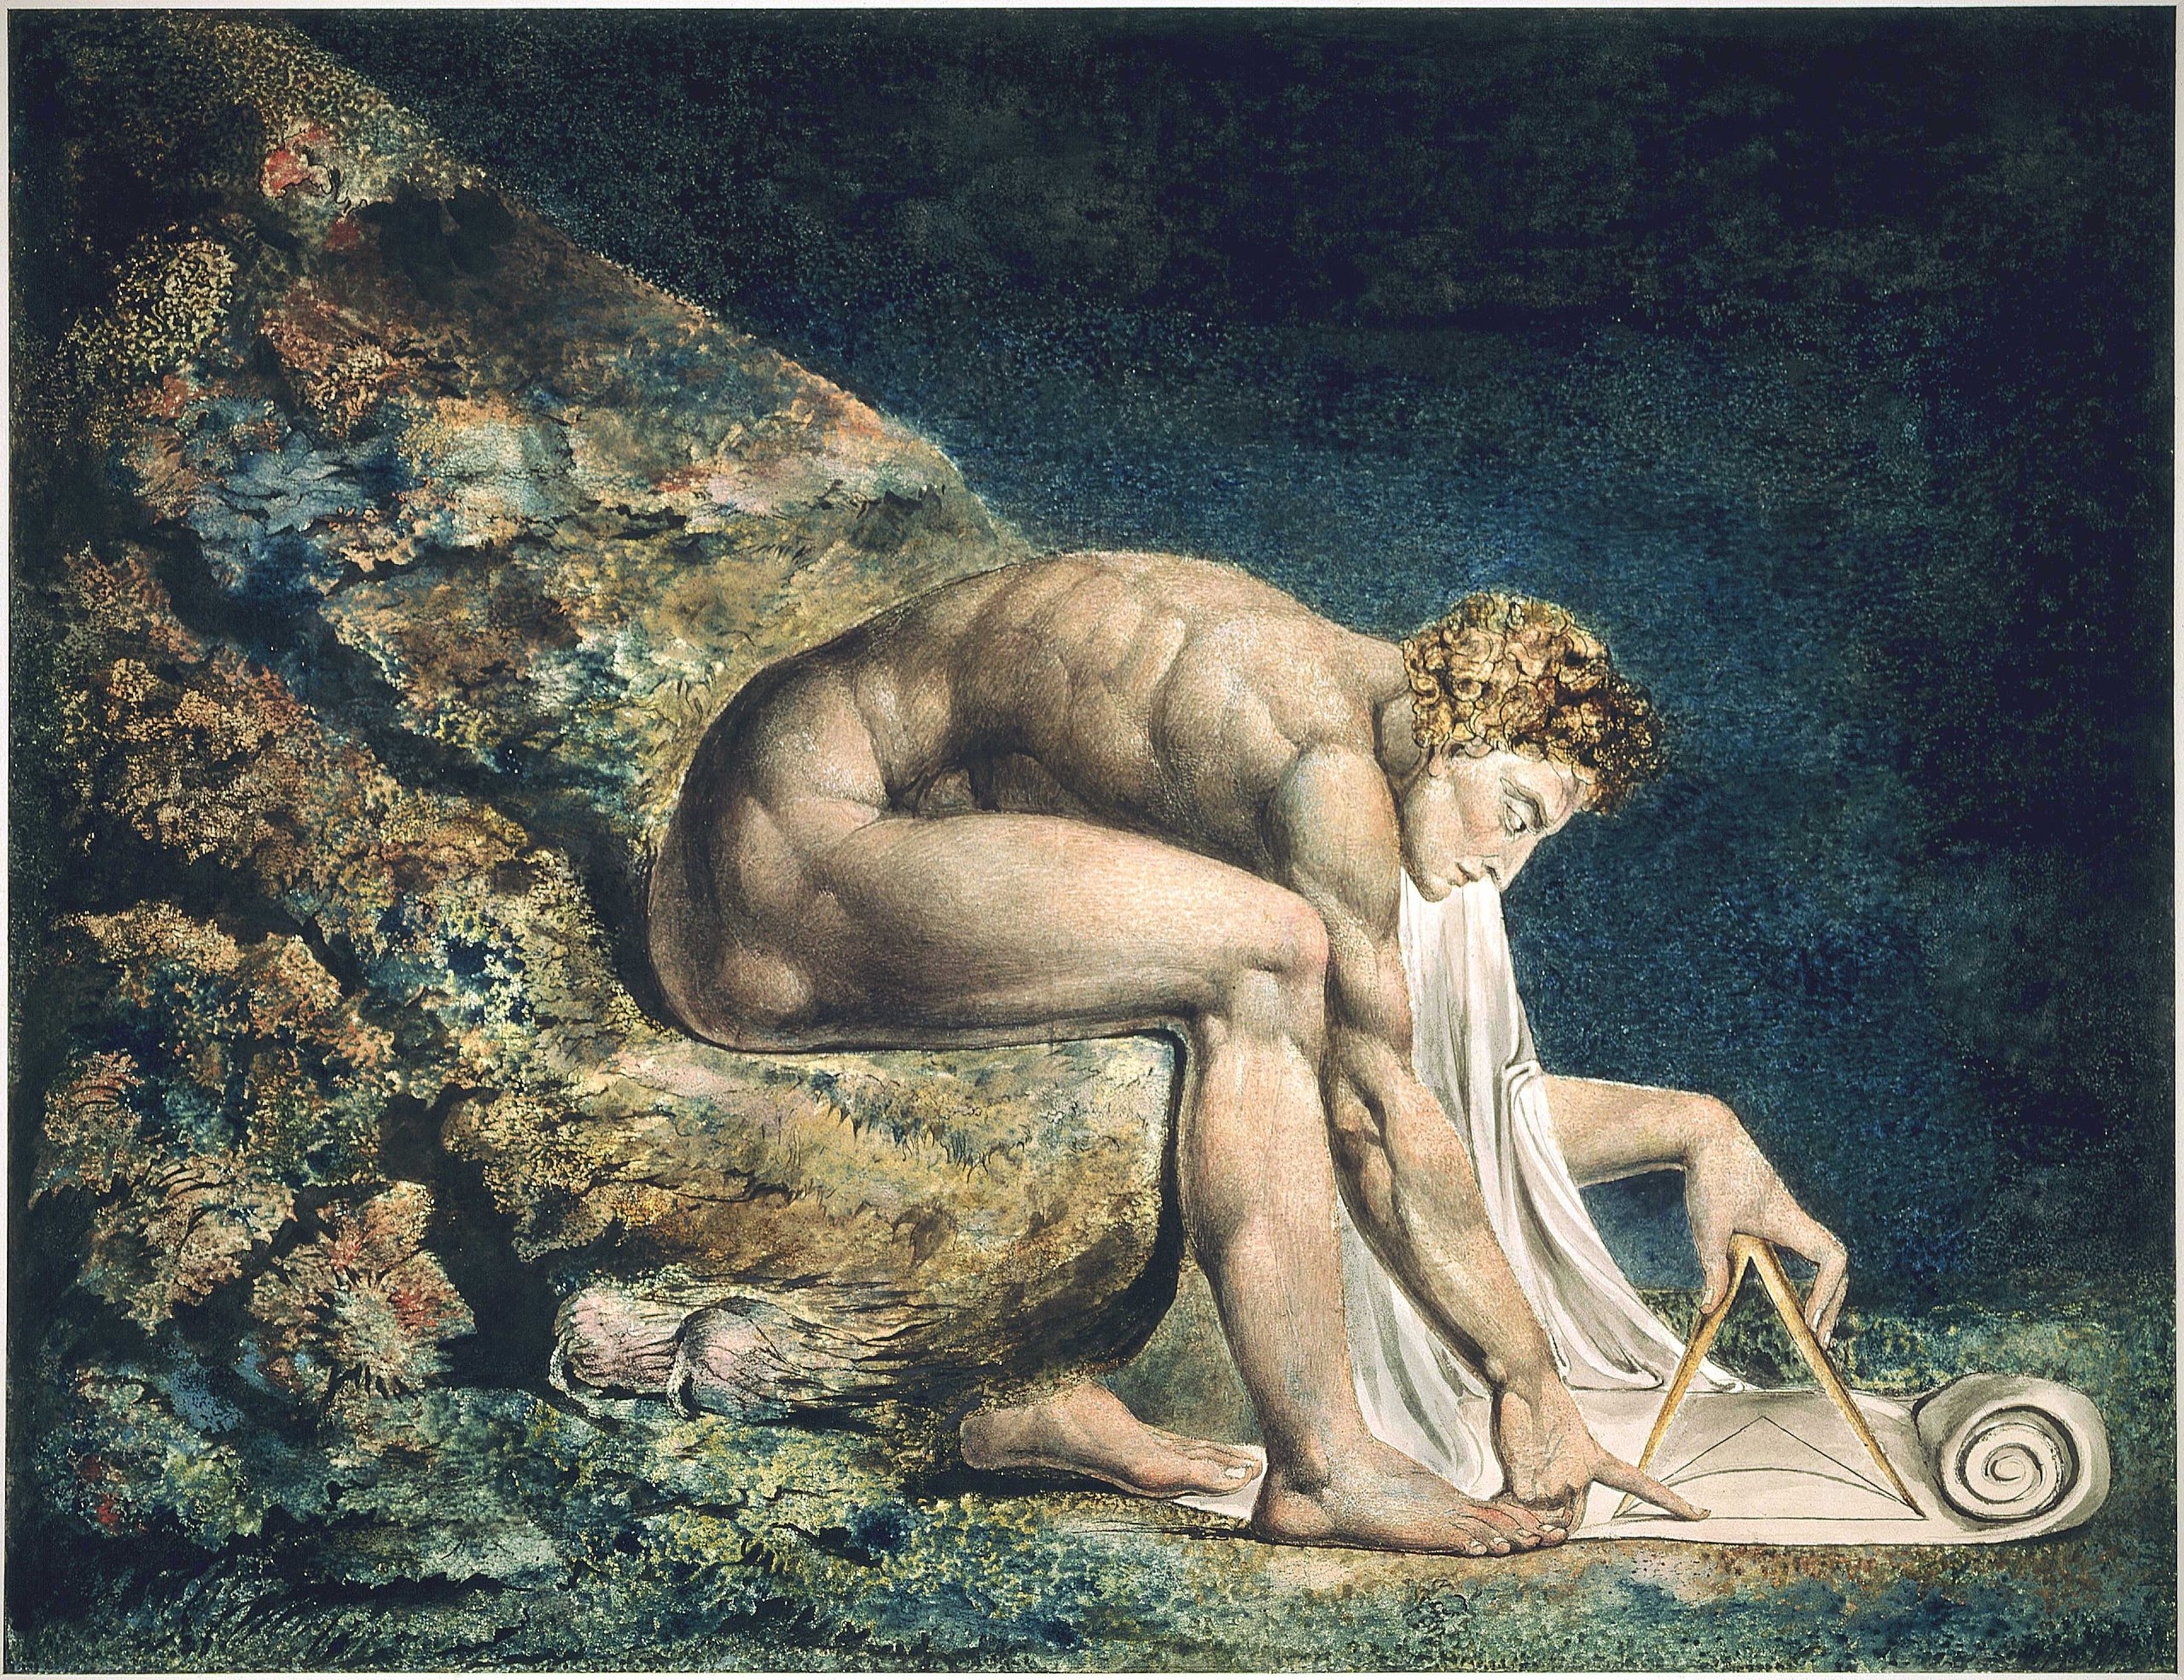
(top image: “Newton”, by William Blake)
Leave a Reply