Tag: Startups

  • The Illiquidity Ratchet

    The Illiquidity Ratchet

    All value created by venture capital, in any vintage and every category, is downstream of the industry’s ability to recognise brilliant individuals and ideas. 

    It is an investment strategy built on discovery. Large pools of institutional capital are diffused through thousands of individual firms, providing broad coverage across industries, geographies and technologies. The failures mostly flare out as cheap experiments, while a handful of outliers produce extreme value. 

    Implicit in this arrangement is venture capital’s need for a healthy market of small firms and emerging managers. Individuals who bring a unique perspective to deployment, with differentiated sourcing and varying models of the world.

    This is the ragged edge of the venture market, maximising the surface area of opportunity.
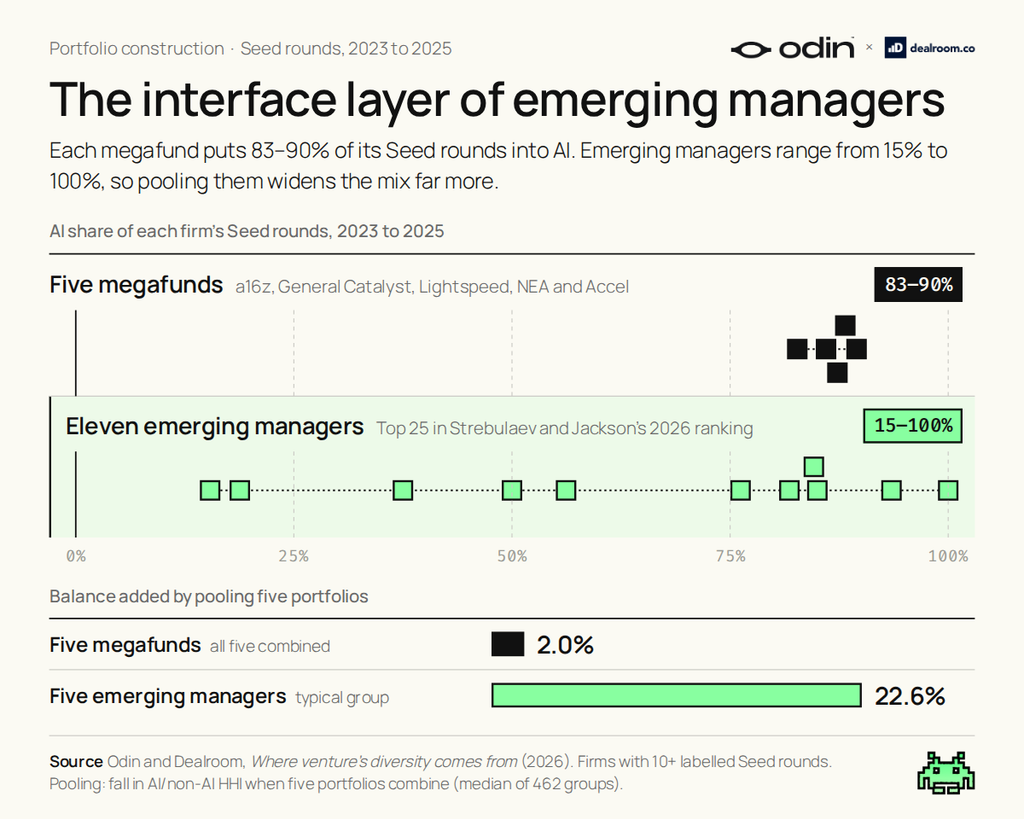
    Over the past 15 years, venture capital has been augmented with a second pool of capital, as much larger LPs entered the strategy when rates were low.

    This flood of capital spawned the “money for winners” megafunds, whose strategy is to double-down on the obviously attractive companies.

    The scale of megafunds has contributed to companies staying private longer, pulling more capital into private markets. At the same time, their LP base is less sensitive to liquidity, able to tap other assets like treasury bills, money-market funds or index holdings for near-term cash needs. 

    Indeed, if you divide the market into funds below $1B as a proxy for “money for experiments”, and funds above $1B as a proxy for “money for winners”, only the latter has really grown. The same is true for rounds above $100M, now clearly the majority of the market —  having been closer to a quarter of total volume a decade ago. 
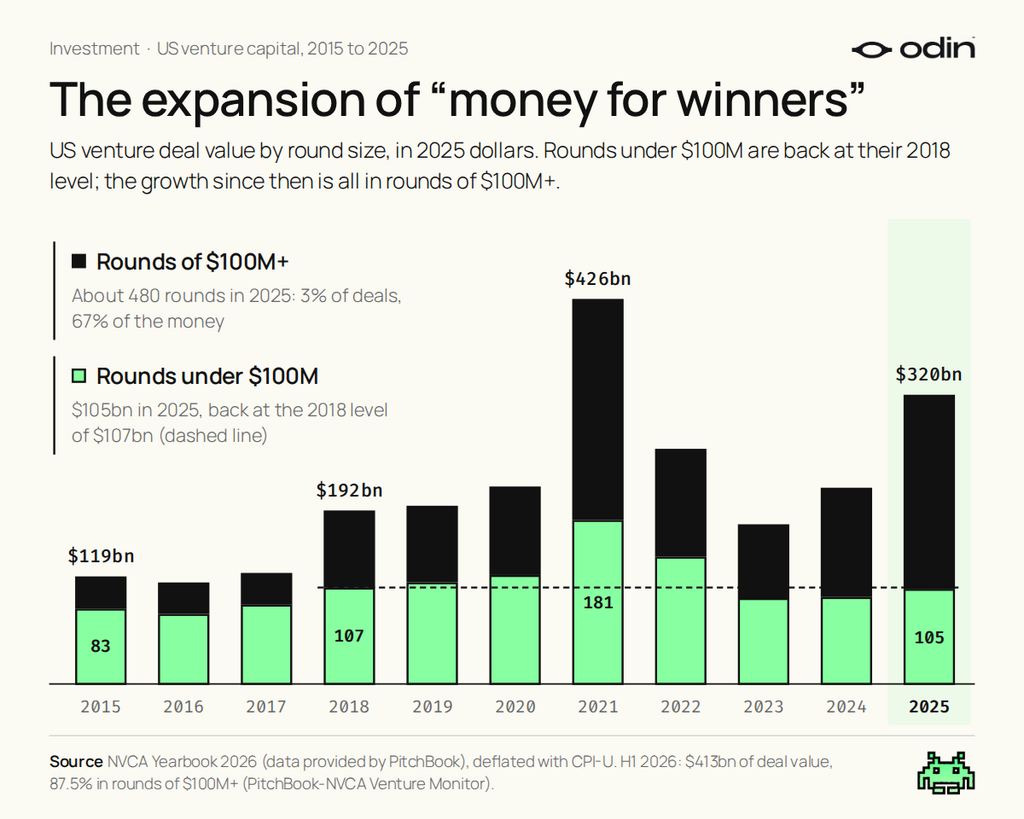
    This increasing top-heaviness is the result of a recursive function where smaller LPs rely on regular liquidity to recycle into new commitments while the larger LPs just want to hold for steady IRR growth — so weak exit markets become a ratchet on fund size. 

    i.e. Small firms started to wash out of the market due to poor liquidity ➔ the venture landscape became narrower ➔ concentration accelerated IRR growth as more capital funneled into fewer companies ➔ megafunds metrics appeared healthy ➔ the top end of the market expands ➔ liquidity weakens further… And on it goes.  
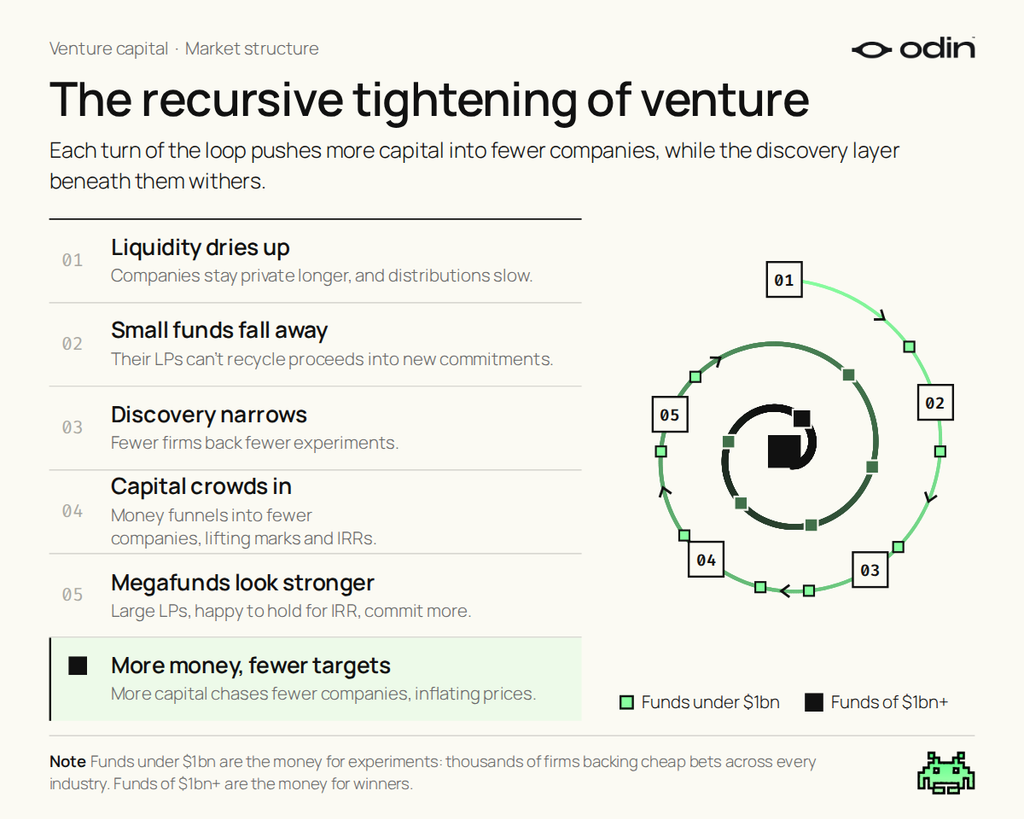
    As a result, the venture market is now awash with “money for winners”, while the discovery layer actually responsible for finding those winners has withered. 

    There is more money than ever for a shrinking number of targets, with much less intellectual bandwidth to ensure it is allocated with care and diligence. This has resulted in inflated prices, herd behavior, and a market that feels increasingly unhinged — with companies like Instinct raising $1B at a $10B valuation, pre-revenue and sans-moat.

    Essentially, if there is no real pressure to regularly reconcile your marks with reality through an exit, you can keep marking your own book as long as you like. Eventually, and inevitably, that spirals until all contact with reality is lost. 
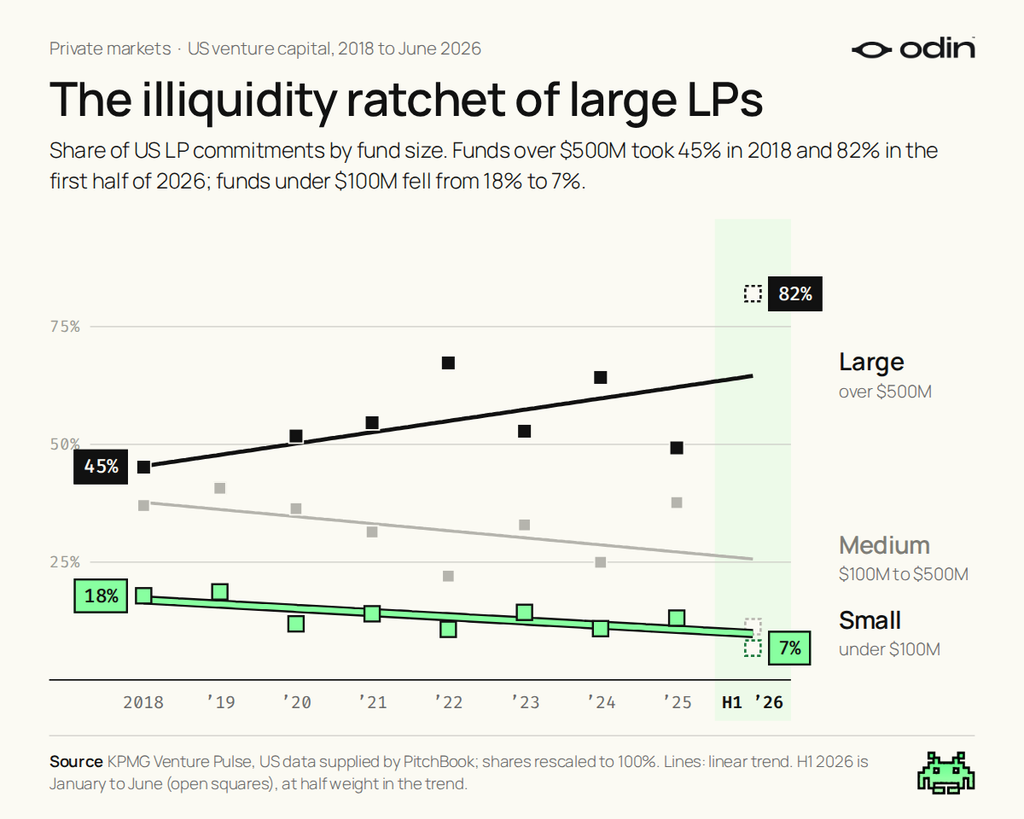
    Up to now, the megafund concept has been justified by the need for large LPs to make large individual commitments, where many smaller commitments would create a burden of admin and management. However, their divergent priorities (lower hurdle for performance, effectively no real need for liquidity) have created an imbalance in the market, and whatever metrics they do generate are increasingly divorced from reality. 

    There is a simple and well-established remedy to this: the fund of funds. 

    “Venture FoFs offer a streamlined alternative, often providing better access, superior diversification, and historically strong net performance, despite the additional fees. They also provide the benefits of operational efficiencies, downside protection, and vintage year diversification.”

    John Felix, Pattern Ventures

    Traditionally this intermediary structure has been looked down on for adding another layer of fees between the LP and the GPs. However, there’s a growing body of evidence that FoFs offer slight outperformance, net of fees, by applying a specialist focus to the otherwise intensive challenge of sourcing and picking managers — a process which few LPs resource properly and even fewer truly understand.   

    Another proposition of the megafunds is access to the most attractive growth opportunities, which may be challenging to reach directly. 

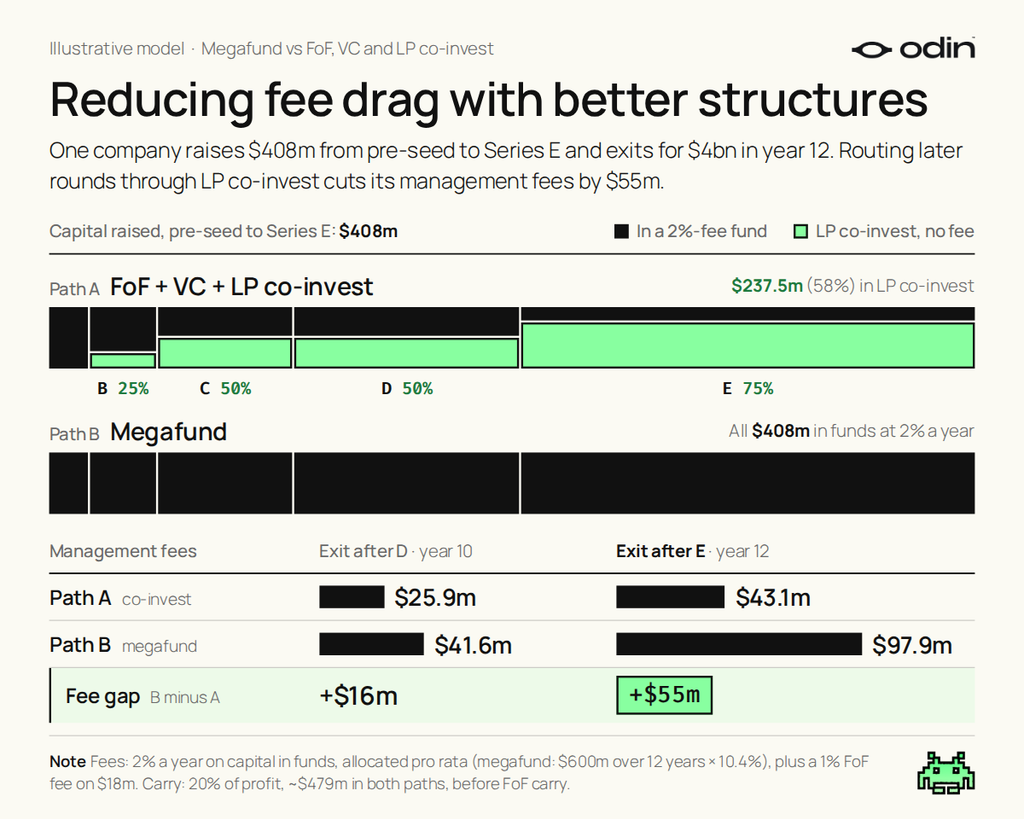
    However, as LPs become more sophisticated about co-invest opportunities, they can get a similar level of access with little of the usual fee drag. Indeed, the shift toward much more substantial co-invest would dramatically lift performance across the market, which is why private equity also evolved further in that direction. 
    Finally, there is the simple truth that small funds outperform large funds, across every fund industry and in every study. According to analysis by Santé, funds of less than $350M are roughly 50% more likely to achieve returns above 2.5x, versus funds of $750M or more. Smaller funds generate a cumulative IRR of 17.4%, versus just 9.7% for the larger bracket.

    “Mega-rounds have a higher floor & lower ceiling. They are less sensitive to improvements in exit rate & exit value. For traditional VC investments, a 10% increase in exit rate & 20% in average exit value generates an incremental 0.43x and 0.44x in Fund TVPI, compared to just 0.19x and 0.35x for funds investing in mega-rounds. Finally, mega-rounds are highly sensitive to the Market Regime and require an active IPO window to achieve the exit performance outlined here”

    Why Venture Capital Does Not Scale (2023)

    So, a fund of funds offers net outperformance already versus direct fund investing, it also enables a larger co-invest book for access without fees, and you make access to better-performing small funds viable for large LPs. In turn, the lower cost of capital is passed on to founders and reduces the risk associated with raising venture capital. 

    “Strategies for investing in direct funds may be constrained by limits on fund access or manager selection skills. We show that VC FoFs often outperform direct investing handicapped by these limitations.”

    Financial intermediation in private equity: How well do funds of funds perform? (2018)

    The outcome is a broad-based performance lift for LPs, and a more competitive industry that is better structured for finding and funding outliers. Stronger short-term returns by eliminating selection difficulties and fee drag, and a market structure that preserves long-term value creation rather than fee extraction.

    Another interesting possibility arises out of this; the great hope of an algorithmic approach to venture capital.

    The extreme idiosyncracy and unpredictability of venture investments means that systematic decision-making can at most exclude predictably bad investments. You cannot find succssful investments with a data-driven approach, because the successes are inherently outliers.

    However, the same may not be true for investing at the LP level. Success as a venture capitalist may involve predictive traits or features which allow an algorithmic approach to offer an edge.

    “Measures of fundraising success, although correlated to most fund characteristics, are not related to future performance. Meanwhile, machine learning tools can use qualitative information to predict future fund performance: the performance spread between the funds within the top quartile and the lowest quartile of predicted probability of success is about 9% per annum.”

    Limited Partners versus Unlimited Machines; Artificial Intelligence and the Performance of Private Equity Funds (2024)

    The implication here is that the fund of funds model is scalable in a way that venture capital is not. These vehicles may be the elastic buckets of market beta which large LPs have been looking for, and they don’t run the risk of cannibalising the long-term growth of the market.

    On top of that, there’s a good argument for an intermediary layer which separates large institutional LPs from the managers. They aren’t exposed to reputational backlash if a manager they have selected invests in dystopian sex work platforms, crypto schemes or exploitative gambling applications.

    This is not to say megafunds are going anywhere; they offer risk-averse institutions the big-brand trust of a KPMG or PwC. However, it seems inevitable that (as in other fund industries) their fee percentage is going to have to compress in recognition of the reality of their performance — which also raises questions about the persistence of their “access” edge.

    If the market returns to its earlier balance, with more capital being funnelled into small and emerging managers via fund of funds products, alongside the lower fee megafunds, it will be able to settle into a productive equilibrium. Whether that will look more like the mix in 2020, or in 2015, it’s hard to say, but the status quo seems unsustainable. 


    Top image: The Great Day of His Wrath, by John Martin (1851-1852)
  • What Does “Founder Friendly” Mean?

    What Does “Founder Friendly” Mean?

    What does a founder friendly investor actually do?

    Is it…

    • …the firm that is the most pleasant to work with?
    • …the firm with the most capital to deploy?
    • …the firm with the most powerful network?

    Or is about alignment with a founder’s long-term succes?

    The answer ought to be obvious, and yet the revealed preference of the industry is to broadcast founder friendly vibes structuring the market to undermine their future.

    For example, a puzzling feature of venture capital that has appeared recently: investors telling (AI) founders that now is a good time to sell their companies.

    They’re probably not wrong, but who is that advice for?

    It’s not for any founder pursuing their life’s work. Nobody who wants to retain control, stay in “founder mode” and build a company of generational importance.

    Instead, this attitude seems to be aimed at mercenaries; companies destined for a quick flip to an incumbent. Indeed, the majority of exit activity has shifted from IPOs to “BigTech acquisitions”, as larger VC firms have become more cowardly.

    “In this paper, we argue that this focus on exit, particularly exit by acquisition, is pathological. It leads to concentration in the tech industry, reinforcing the power of dominant firms. It short-circuits the development of truly disruptive new technologies that have historically displaced incumbents in innovative industries. And because incumbents often buy startups only to shut them down, intentionally or not, it means that the public loses access to many of the most promising new technologies Silicon Valley has developed.”

    Exit Strategy (2020)

    What happened to finding founders who were on a mission to change the world?

    Isn’t venture capital supposed to support the most important companies, driving progress, creating prosperity?

    Where are they supposed to turn, otherwise?

    It’s tragic that the dominant firms in venture capital have switched from financing creative destruction to the safer and easier role of serving incremental solutions to incumbents.

    Of course, this is likely the natural consequence of venture capital firms themselves becoming bloated, risk-averse incumbents. The product they serve to LPs is stability and predictability, not risk-seeking alpha.

    So, if a company does not choose to exit to an incumbent, or that option isn’t readily available, what then?

    Increasingly, they are only funded into the later stages if they are a useful vessel for allocation — a vehicle by which VCs can justify fee income on ever-larger pools of capital. Private market sponges, with failing health and indefinitely postponed exits.

    This also ends badly for the founder.

    This is where the VC market is in a real pickle.

    The case is crystal clear and yet nobody can admit to it, because it’s both extremely proifitable and hostile to founders.

    “It is difficult to get a man to understand something, when his salary depends on his not understanding it.”

    Upton Sinclair

    Raising more private capital is correlated with worse long-term performance, and it gets increasingly worse with scale. Of the 12 companies who have raised >$3B and listed in the US, 11 have (dramatically) underperformed the index.

    These were the darlings of venture capital, the companies which raised unprecedented amounts. Then they were dumped on public markets and left to struggle.

    The reasoning is simple: Private and public markets have different goals, reflected by how they value companies.

    • Private companies are valued on their fundraising momentum, which is a result of ARR and market narratives. Thus, companies are rocket ships with weak economics.
    • Public companies are valued on a relatively thorough examination of their financial health. Narratives matter, but hype competes directly with pressure from short sellers.

    As a result, the longer a company stays private, the more of a struggle it will be to adapt to public markets.

    It even appears that giant growth-stage rounds don’t even perform particularly well for VCs, but the goal isn’t performance, it’s allocation. Capital at work. AUM. Fees. Rent-seeking. And then inventing new ways to dump these bags on others.

    It’s great that we’ve moved on from the era of replacing founders and rushing companies to IPO for grandstanding purposes. But what has replaced it is arguably much worse.

    Consider that tech is still dominated by the Mag-7; companies mostly founded in the 70s or 90s. Companies that are now worth trillions, who originally raised peanuts and went public in a median of less than six years.

    So, founders appear to have two main choices if they take VC:

    • Take a quick flip to an incumbent if your future looks dicey.
    • Stay private and absorb capital until it becomes toxic.

    The default used to be a sensible middle path: raise the capital you need to build a great business, take it public, and thrive.

    Unfortunately, this outcome does not serve the platform firms whose main challenge is allocation at scale. So, liquidity has evaporated, smaller firms have suffered, and founders are more often stuck with these incentives.

    Of course, founders have agency. They are able to determine their future, providing they are fully aware of the options and consequences.

    Indeed, some founders may understand the importance of hitting an exit at the right time, and in the right shape, to maximise the future of their company. They have the potential to do exceptionally well.

    However, their advisors on financing are usually venture capitalists, who are not incentivised to understand why too much private capital is bad for a company.

    In fact, they are incentivsed to keep stuffing capital into attractive assets until they are no longer attractive assets.

    So, the smart path isn’t easy or obvious, for the founder.

    Getting an exit right requires nothing short of good timing, brilliant execution, and awareness that their future interests will eventually fall out of alignment with even the most “founder friendly” venture capital firm.

    (top image: Michelangelo’s “The Torment of Saint Anthony” )

  • The Tyranny of Revenue

    The Tyranny of Revenue

    Private markets have inherited the curse of myopia

    It’s a long held belief that public markets may be a poor environment for innovation because of the short-term focus driven by meeting quarterly targets.

    However, there’s an indication that this has reversed.

    Research from the 1990s and early 2000s did indicate that public companies invested less, and were less responsive to investment opportunities than matched private peers, as a reflection of limited long-term thinking in their strategy.

    “Listed firms invest less and are less responsive to changes in investment opportunities compared to observably similar, matched private firms, especially in industries in which stock prices are particularly sensitive to current earnings.”

    Comparing the Investment Behavior of Public and Private Firms, by John Asker, Joan Farre-Mensa and Alexander Ljungqvist

    However, this does not appear to be the case in more recent analysis. In a relative sense, comparing public companies to matched private companies, public companies now appear to be more long-term oriented than their private peers.

    “IPO firms respond more to investment opportunities and have higher productivity in their early public years. Our results on public firms’ sensitivity to growth opportunities hold under several robustness tests, including when we consider firms’ total growth including acquisitions.”

    Do IPO Firms Become Myopic?, by Vojislav Maksimovic, Gordon Phillips and Liu Yang

    What has changed over the course of the last 25 years which could explain this? Primarily, the volume of capital in private markets, and the scale of exits.

    Venture capital has evolved from the business of funding cheap / high ROI experiments to the business of fuelling market expansion. As a result, it has inherited what was once a public market problem; the need to regularly demonstrate growth in order to boost share price.

    Today, revenue targets for the various staged funding rounds are surging, as expectations climb higher and creep earlier.

    In the late 2010s it was assumed that a company could comfortably hit a Series A with around $1M in revenue. That rose to $2-3M by 2024, and with AI the bar has been pushed even further in the years since.

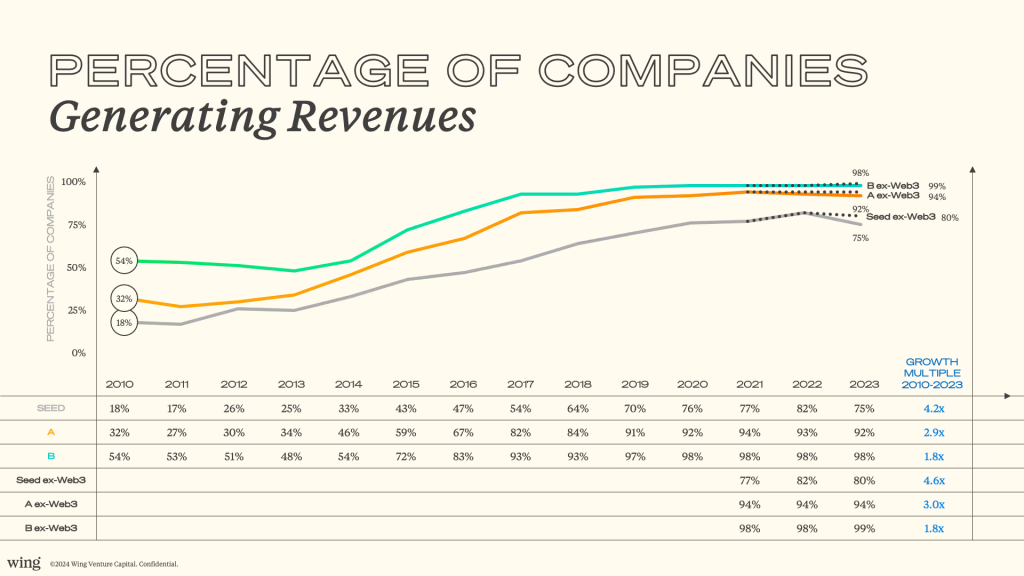
    Consider data from Wing. Only 32% of Series A companies had any revenue at all in 2010, growing to 92% by 2023.

    More than ever, venture capitalists want to see revenue. And once you have revenue, it will never be enough.

    The resulting myopia problem is a real problem for innovation, and there’s both a robust empirical case and a important anecdotal case to be made.

    The Academic Case

    First up, the data. There’s a strong case made across a number of papers about the dangers of startups scaling too soon, and too quickly.

    “We find that startups that begin scaling within the first 12 months of their founding are 20–40% more likely to fail… [We also find] no evidence of a countervailing benefit in terms of successful exit.”

    When Do Startups Scale? Large-scale Evidence from Job Postings, by Saerom (Ronnie) Lee and J. Daniel Kim

    “For the last 6 months the Startup Genome Project has been researching what makes high growth technology startups successful and has gathered data on more than 3200 startups. In our research one reason for failure has shown up again and again: premature scaling.”

    Startup Genome Report Extra on Premature Scaling, Max Marmer, Bjoern Lasse Herrmann, Ertan Dogrultan and Ron Berman

    To provide a summary of the obvious, it is crucial that startups scale properly across all dimensions as they develop. They must be testing and validating assumptions, adding the right skills at the right time, and building the right core of knowledge.

    If you want long-term compounding growth from a genuinely important company, it probably doesn’t start with a mad dash to build a flimsy book of contracted ARR.

    When startups are pushed — by the incentives presented by investors — to pursue “growth at all costs”, this obviously produces much more brittle businesses. As a result, they fail more often, innovate less, have higher rates of fraud, and produce worse exits.

    The Anecdotal Case

    It’s an interesting thought-experiment to apply this question of short-termism and long-termism to the world of AI.

    On one hand, there is Google, a public company. Fundamentally, today’s AI industry would not exist without Google, DeepMind, and their pioneering work on the transformer architecture.

    While they’ve been slower to commercialise the technology than some of their private peers, they have caught up quickly and regularly trade the top-spot on benchmarks with the other labs.

    Perhaps, more importantly, is the calm demeanour and steady leadership reflected by Demis Hassabis. He talks about science, curing disease, and other productive applications of the technology with giddy optimism.

    There’s a particularly powerful scene in the Thinking Game documentary where Demis comes to the conclusion that they should predict every protein sequence in existence and release the data for free to spur further discoveries.

    On the other hand, there is the temperamental nature of leadership at the private labs. Altman and Amodei have spent years making reckless claims about AGI, the end of employment and parallels to weapons of mass destruction.1

    This is not intended to downplay the impact of these models. There are real concerns about changes to the job market, and to cybersecurity. But for a technology is so consequential, who would you prefer as a steward? Sam “Code Red” Altman, Dario “Oppenheimer” Amodei, or Demis Hassabis?

    The truth is that Altman and Amodei are bound by the need to play the private market game. If either one of them falls significantly behind on revenue growth, investors will herd toward their competitor. So, they are stuck in an incremental battle for market share and short-term narrative victories. They are slaves to the needs of their investors, inflating the impact of their work beyond all reason.

    Meanwhile, Hassabis is quietly building. He does not need to go on speaking tours, drum-up investor interest or pump the market with irrational sentiment. He’s responsible (along with the other great researchers across Google) for far more important innovation than the other private labs combined.

    In this example, it is clearly the public market tortoise that is beating the private market hare in the long-run.

    Private Market Myopia

    The tragedy of a more myopic private market is that even as it grows in scale and scope, it is not able to fund the innovations which have been crying out for more patient capital.

    Instead of driving capital into long-horizon infrastructure and industrial capacity, swollen private markets pursue endless incrementalism — an acusation they have commonly levelled at the public markets.

    Worse still, is this myopia feeds investment in short-term opportunities that cannibalise long-term prosperity. Predatory lending companies, “pay-to-earn” scams, expense gambling apps and crypto casinos. These well-funded corners of the market are not only an opportunity cost for real innovation, but are actively cannibalising future potential.

    So, yes. The world will need more great public companies to help dig us out of this casino economy.

    1. Occasionally with times and locations that coincided with major private market fundraising activity. [↩]
  • Designers of Problems Worth Solving

    Designers of Problems Worth Solving

    Why the most investible founders might have the least fundable ideas

    “What do you look for? Grit — sure… everyone likes to say that… intelligence… obviously — the right balance of taking feedback & independence — sure. But you have to go deeper — have a deeper framework on really what makes for great founders who are going to stick it through and be winners AND what is the shorthand you can share with your partners / each other on WHY you as a lead investor actually believe in this person / the bet you are making.”

    Sam Lessin, GP at Slow (Draft letter to LPs)

    Four basic premises for early-stage investing:

    Accepting all of these means acknowledging that first-check VCs should generally source their own deals without relying heavily on signals like traction, market activity, or credentials.

    This is the torturous reality of being the first money in: reaching conviction on little more than a story.

    And you must be able to do that in a thoughtful manner that can be explained to others, and learned from in future.

    A Complicated Package

    The “jockey’s versus horses” debate goes back to the very beginnings of venture capital. It has also become painfully reductive: given a choice between markets, technologies or people, being explicitly pro-founder has the best optics.

    Of course, it’s never that simple. All information is useful in the decision-making process, and each aspect tells you something valuable about the others.

    • The approach described by Peter Thiel is to consider the whole pitch as “some kind of complicated package deal,” combining people, ideas and technology.
    • Or, as Nabeel Hyatt puts it, the way to “separate hucksters who do a good pitch from people who are real executors is to look at the thing that comes out of their hands”.
    • Indeed, Sam Altman described the Y Combinator screening process as looking closely at the “non-obvious brilliance of the idea” being presented.

    Indeed, the problem a person chooses to solve, and how they approach solving it, can tell you a lot about the person..

    Another way to frame this is outlined by Mattia Bianchi and Roberto Verganti in “Entrepreneurs as Designers of Problems Worth Solving“:

    “Finding meaningful problems to address is a critical driver of innovation and entrepreneurship in today’s turbulent environment, possibly even more so than problem solving.”

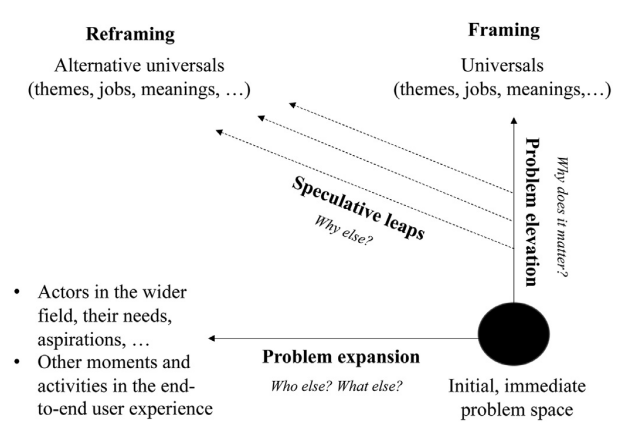
    “Designing a problem is mainly based on inventively reframing a situation through its expansion, elevation, and prospective sensemaking. The outcome is a more meaningful problem when it aligns the entrepreneur’s purpose with how society, technology, and culture are changing.”

    Entrepreneurs as designers of problems worth solving

    Bianchi and Verganti’s suggestion is that the act of identifying important problems is itself indicative of potential, and a precursor to “designing problems”: the addition of novel aspects which weren’t part of the original problem scope.

    Problem expansion, elevation, and speculative leaps for designing novel
    problems

    This process demonstrates that a founding team has a deep understanding of a particular problem (and the universe around it) and a novel and thoughtful solution.

    Finding Outliers and Avoiding Hucksters

    Understanding and evaluating qualitative traits is obviously very difficult, especially when the playbook of what VCs say they look for is now wide-open for study.

    However, while there’s a strong canon of common wisdom about the attributes of “good founders”, very few VCs have build a framework for recognising, documenting and reflecting on them.

    An example framework that overlaps with the “problem design” approach is the list of attributes used by 1517 Fund, as described in Michael Gibson’s book, ‘Paper Belt on Fire‘:

    • Edge control
    • Crawl-walk-run
    • Hyperfluency
    • Emotional depth & resilience
    • Sustaining motivation
    • The alpha-gamma tensive brilliance
    • Egoless ambition
    • Friday-night-Dyson-sphere
    • Wily & wondrous
    • Alchemy

    (Descriptions and examples for the first 8 are included in the book. The final two may be included in a forthcoming update.)

    If you study these attributes, and the story behind them, you will understand an important qualification: they reflect markers of outlier behavior. The intent is to seek out extraordinary people, rather than create template for ordinary brilliance.

    Indeed, the industry’s more common reliance on gut-feel and credentials is likely to exclude outliers, and limits the potential for constructive reflection on (and true accountability for) investment decisions:

    “For example, VCs often discuss the ‘chemistry’ between themselves and the entrepreneur. The deal often falls through if the chemistry is not right. Such intuitive, or “gut feel”, decision making is difficult to quantify or objectively analyze.

    The added complexity from subjective information further clouds the decision making process and invites the decision maker toward more biases. Due to the complexity of the decision and the VCs’ intuitive approach, VCs may have a difficult time introspecting about their decision process. In other words, VCs do not have a comprehensive understanding of how they make the decision.”

    A lack of insight: do venture capitalists really understand their own decision process?

    There are two typical outcomes of this laziness:

    Instead, the best way to understand something like determination or clarity might be to look for founders with a well-designed problem. For example, making humanity multi-planetary, making energy too cheap to meter, tapping atmospheric rivers, or building the telescope for drug discovery.

    • If a founder has designed a problem which seems high on importance and low on popularity with investors, they’re likely in it for the right reasons.
    • If they can articulate the problem in a novel and coherent manner then there’s a good chance they’ll be able to find a solution where others will fail.
    • If the story of that “problem design” process feels deeply personal (it keeps them awake at night, and busy on weekends) there’s a good chance they will persevere.
    • If their approach to the problem shows a willingness to go back to basics and do the work to learn whatever is required, they likely have the agency required for entrepreneurship.

    It doesn’t matter if the founder ends up pivoting. That may even be desirable. It doesn’t alter the value of what you can learn from their approach to designing and solving problems.

    Thus, some of the least obviously “fundable” ideas may be the most deserving of investment, if you use the right lens. Investors should seek founders that have picked good quests over those that choose lower friction.

    Conspicuous Consumption

    At the opposite end of this spectrum are rage bait startups and the blight of limbic capitalism.

    It is no coincidence that these companies are always at the dead-centre of consensus. The playbook is simple:

    1. Build in a competitive category
    2. Pursue viral stunts that make you unignorable
    3. Raise a huge round to fund more virality / growth

    This exploit a basic premise of scaled venture capital: the largest firms cannot afford to miss potential winners.

    A startup can look like a potential winner by having a track record of success, a density of technical talent, or by commanding enough attention to become an object of desire; the ‘conspicuous consumption‘ of venture activity.

    As long as they pass one of these legibility tests, they get onto the treadmill of “tier-1 VC” convention bidding where success is hitting milestones to earn staying on the treadmill. Capital feeds growth on hype-adjusted multiples, producing fuzzy venture math which is capable of any conclusion you desire.

    The only problem these companies truly solve is scaled capital allocation and systematic AUM growth for venture capital firms. The founder becomes a minor player in a largely commensal relationship designed to support the VC’s ambitions.

    “The hyper-normative world of consensus-seeking is dripping with incentives that would make you their slave. And if you don’t have anything, in particular, that you believe, then they will likely succeed.”

    Build What’s Fundable

    Fund Good Quests

    Without revisiting the topic of bifurcation yet again, it is clear that one of the models described above works for traditional VCs, while the other is geared toward the scaled allocators.

    So, if you are an early stage investor, one of the best things you can ask yourself in the early stages of evaluating a company is whether the founders are designers of a problem worth solving.

    It may not lead you to companies that grow rapidly, which may make raising your next fund more of a challenge. But, like proper risk management, it’s the right approach if you really care about maximising returns and building a durable legacy as a venture investor.

    (top image: “Astronomer Copernicus“/ “Conversations with God”, by Jan Matejko)

  • Coordinating Capital

    Coordinating Capital

    The role of startup valuation in staged capital deployment

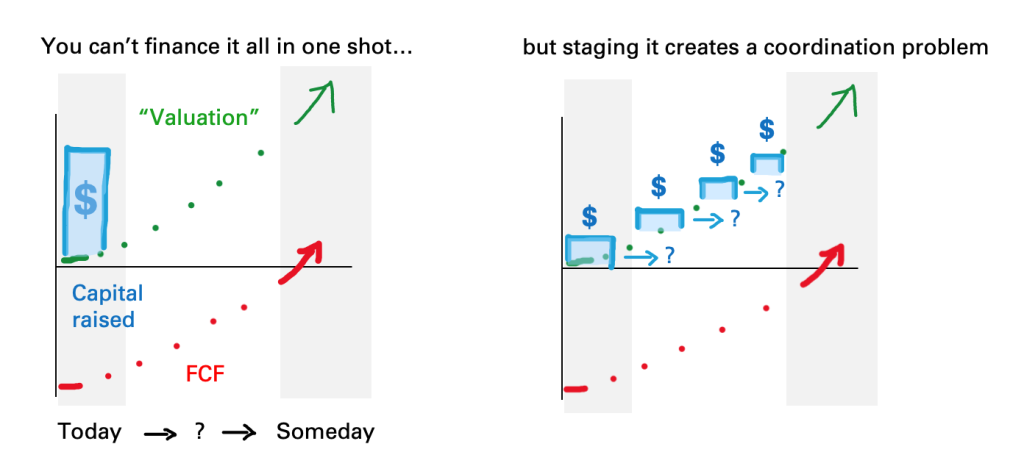
    In his article VCs should play bridge, Alex Danco described the Capital Coordination problem in venture capital, created by the staged nature of investments.

    I recommend reading the whole piece, but the summary is that investments are de-risked by staging capital over future milestones (with the implied valuation step-ups) rather than investing everything up-front and hoping for the best.

    The heart of this strategy is the signalling game where investors offer affirmation of the investment for their capital partners.

    VCs should play bridge

    “This gives the next investor cover to say, ok, I’ll do the same thing. I’ll invest at $20M, sending a signal: I believe that this price reflects a discount to the next round. This 20 million price, by current convention, means we believe this hand will play out as another X million in GMV run rate”, or whatever it is your signalling for this new round of bidding.”

    Danco’s assessment speaks to the oddly myopic perspective of “venture math“: investors are primarily focused on understanding incremental progress (measured with ARR) rather than the ultimate outcome. This has come at a cost to sectors that are slower to start generating revenue but solve much more important problems.

    He’s right to frame venture capital as collaborative (Bridge) rather than strictly adversarial (Poker), this also highlights issues like enmeshment and collusion which emerge when so much stress is put on relationship-driven outcomes over objective measurement.

    The approach that Danco describes as “convention bidding” is framed as an alternative to the zero-sum attitude of formal valuation — where investors are primarily concerned with securing their own returns rather than participating in affirmative semaphore.

    Indeed, this reflects a revealed preference for market signals over conviction which should trouble anyone who still believes venture capital is responsible for risk capital formation.

    Discounting the Future

    Further to the above, Danco’s article is a good reflection of venture capital’s poor grasp of valuation, characterised by three common misconceptions:

    1. Valuation is transient, and at each stage a new valuation would need to be calculated — creating uncertainty that threatens signal-driven coordination.
    2. Valuation is the same as price, and entry points are more a function of market norms and comps than they are of fundamental value creation.
    3. The practice of valuation is built on too much uncertainty to be practical for early stage companies.

    While the first is inaccurate, the second is actually dangerous. The general practice of market-driven pricing has created huge structural fragility in venture capital, exacerbating the already painfully boom-and-bust nature.

    The third, however, is just silly. All investments are predicated on valuation, at least in theory (the alternative being mindless momentum investing). The only difference is whether it’s written out with explicit assumptions or a mental calculation with implicit assumptions.

    Indeed, valuation is essentially the story of a startup (“What happens if things go right?”) translated into numbers, with some discounting for the cost of capital and risk of failure. You can think of it as the financial source code of a pitch.

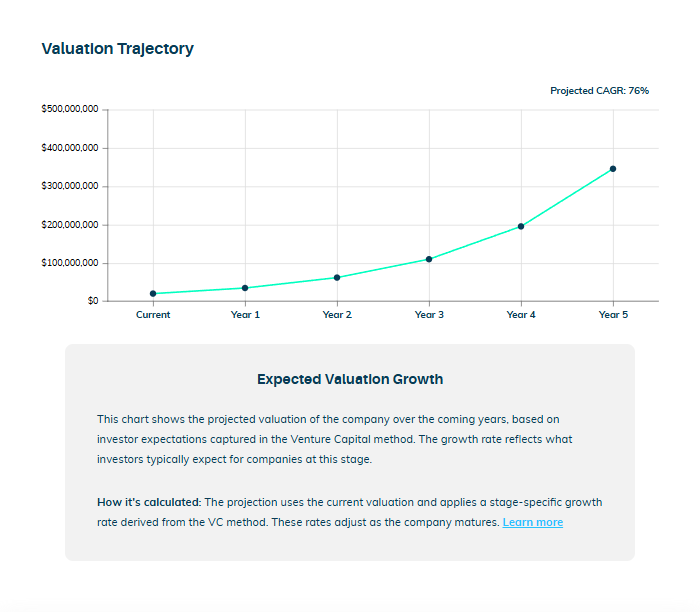
    Usefully, by calculating a terminal value based on that story and discounting it using the expected rate of return in venture capital, you can also ascertain a healthy entry point for future rounds — assuming the startup remains broadly on track.

    Consider the below: the valuation of a Seed round, calculated on Equidam at just over $20M. As a part of this calculation, and the future it’s predicated on, you can also see the valuation trajectory for the forecasted period. If the company raised a Series A at ~30 months, the valuation would be around $85M.

    Expected Valuation Growth – Equidam

    Of course, all of the usual caveats: the future is uncertain, startups pivot, markets shift. However, it’s fairly easy to built those adjustments into a model and see how they change both today’s valuation and the future trajectory.

    Assessing valuation with a higher resolution view of performance enables better judgements: Perhaps top-line revenue is growing on track, but costs are surging. Maybe revenue is lagging, but margins are way better than expected.

    The hope is not that forecasts play out precisely, but that they give you a useful relative perspective on performance over time.

    If venture capitalists wanted a way to coordinate staged capital in the future, to finance a company efficiently (with minimal time spent agonising over terms) while ensuring a good risk-adjusted return for all investors, this is the logical approach.

    Valuation is essentially the process of aligning expectations across market participants by transparently exploring data and assumptions. Typically this occurs between buyer and seller (VC and founder) in a specific transaction, but there’s no reason why downstream capital providers couldn’t benefit from that work.

    It also offers the vital benefits of helping investors better understand the value of novel innovation, and limiting exposure to systematic risk of market-based pricing — getting caught in the trap of “money chasing deals“.

    (top image: “The Bulls and Bears in the Market” by William Holbrook Beard)

  • What is Valuation

    What is Valuation

    Whether you’re investing in mature companies in the public market, or fast-growing startups in the private market, one question separates good and bad investors:

    Do you understand valuation?

    Valuation is the rationale by which you determine which opportunities to pursue. To develop your understanding of valuation is to develop your ability to recognise potential.

    Despite the central role in investment decisions, valuation is often misconstrued as financial engineering or market-driven pricing exercises.


    Valuation is an opinion

    Here’s three things valuation is not:

    • Based on verifiable inputs
    • Provably accurate in output
    • A mirror of market sentiment

    Instead, valuation is always an opinion based on a set of assumptions about an unknowable future.

    “People act like it’s an award for past behavior. It’s not. It’s a hurdle for future behavior.”

    Bill Gurley, VC at Benchmark

    Whether that valuation is based on a detailed DCF model or napkin-math, it’s an opinion. And it’s no more or less of an opinion as your process gets more or less sophisticated; the only difference is how clearly you outline the assumptions.

    When one investor states that a company is overpriced, and another that it is undervalued, neither is right or wrong in the moment — they just have differing opinions.

    Valuation can be a simple, implicit part of the process, or it can be an explicit exercise used to better understand an opportunity and check assumptions.

    Valuation is a story about the future

    In order to form an opinion about a particular future, you must first listen to its story.

    “The value of a stock is what people believe it is and could be. A stock is a story.”

    Lulu Cheng Meservey, Founder of ROSTRA

    All investment decisions are bets on today’s fiction.

    • Elon Musk is telling you that we must get to Mars
    • Brian Armstrong is explaining the importance of Bitcoin
    • Parmita Mishra is describing the future of medicine
    • Aaron Slodov is laying out a reindustrialisation roadmap
    • Augustus Doricko is talking about rivers in the sky

    Do you believe them, when they have nothing but a story?

    Does that story involve unleashing a huge amount of economic energy? How much capital does it require?

    Based on the credibility of that story, and the potential scale of that economic energy, is it worth paying-up today?

    “The scarcest resource isn’t capital or talent. It’s the ability to make people believe in your specific tomorrow strongly enough to fund it today.”

    Howard Yu, LEGO® Professor of Management and Innovation

    Valuation is the art of using stories to develop opinions about the future

    Valuation can be broken down into a few pieces:

    • How do you judge the credibility of a story?
    • How do you estimate the economic potential of a story?
    • How do you estimate the risk associated with a story?

    You can think about this via two extremes:

    1. You’re looking at a company you’re familiar with. You’ve got a good mental model of the industry, the technology, the market forces, trajectory, and risks. It’s relatively simple for you to make a rough judgement on value in your head. This reflects Kahneman’s “System 1” thinking.
    2. You’re looking at a company you have no familiarity with. The technology is novel, the market is emerging, and there’s no real precedent. In order to make a good judgement, you have to submerge yourself in details and scenarios. This reflects Kahneman’s “System 2” thinking.

    In the latter case, a more sophisticated valuation process can help you understand the credibility and economic potential of a story. It provides a framework for ingesting information that can control biases, while allowing you to recognise and scrutinise the main drivers of value.

    Valuation is essentially the act of running simulations of the future described in a story, focused on the numbers rather than the narrative, to explore the potential.

    Pricing is not valuation / Trading is not investing / The present is not the future

    Venture capitalists often choose to focus on relative pricing, instead of valuation, as an attempt to proxy experience through crowdsourced activity — allowing for speedy “System 1” style investment decisions.

    This means analysing industry activity, which biases investment towards categories with low information friction like B2B SaaS, at a cost to sectors with more idiosyncracy, like deeptech.

    Unfortunately that focus on market data also means these investors are not developing their ability to make judgements about the future, only to pattern match today. This compounds into a ‘knowledge worker atrophy‘ problem, weakening venture capital’s institutional competence at funding creative endeavors and novel solutions.

    That would appear to be a critically weak link in the value proposition of venture capital, and the premise that it funds important solutions to humanity’s problems.

  • -1 to 0: Notes on Origination

    -1 to 0: Notes on Origination

    “Small hinges swing wide doors”

    Eric Bahn, Co-founder and GP at Hustle Fund

    Consider this simple truth: All value created from Series A to exit is downstream of the first check. Without initial belief, the foundation of VC collapses.

    This relatively thin slice of venture (by capital) is therefore disproportionately important. All future returns are directly attributable to the industry’s ability to surface new opportunities.

    Despite this fundamental importance, venture capital is structurally rigged against origination:

    • Origination is inherently a small check pursuit, as these ideas need minimal capital to validate propositions.
    • Origination is primarily a small partnership or solo-GP pursuit, versus the consensus-building nature of large firms.
    • LPs are biased against highly diversified VC strategies, particularly with the growth of Fund of Funds, which makes scaling an origination strategy more challenging.

    Thus, origination is the domain of smaller firms, with smaller funds. This runs contrary to the compensation incentives in venture capital, which push successful investors to raise larger funds and invest at later stages.

    “In exploring its sources, we document several additional facts: successful outcomes stem in large part from investing in the right places at the right times; VC firms do not persist in their ability to choose the right places and times to invest; but early success does lead to investing in later rounds and in larger syndicates.”

    The Persistent Effect of Initial Success: Evidence from Venture Capital (2020)

    So, in addition to the existing problem of VC’s lack of institutional knowledge and high churn, good investors are often squeezed out of this origination focus if they wish to achieve greater scale.

    Origination is the foundation on which all future VC returns are built, yet it is systematically underresourced and underallocated

    You should be dubious of any venture capitalist that claims “there’s too much capital, and not enough good opportunities”.

    You will never this claim from VCs focused on origination, who have to spend a distracting amount of time on their own fundraising — even when their track record is strong. Again, their size prohibits them from more easily raising from larger institutions.

    This chronic misalignment sets the ceiling on what venture capital can achieve in returns and accelerated innovation

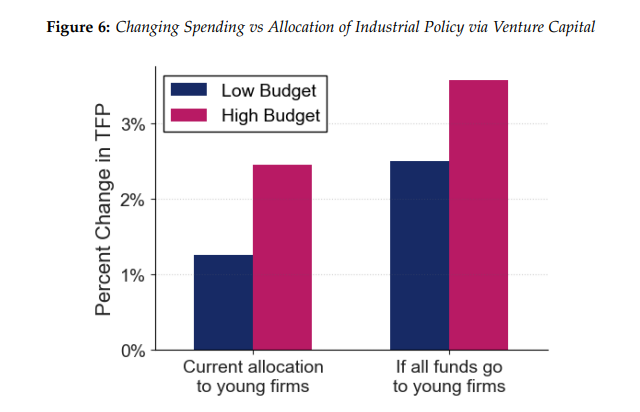
    Multiple studies of the innovation ecosystem in Europe, and how funding is distributed by bodies like the EIF, have come to the same conclusion: Capital allocated to later stages does not solve the problem of underpeformance and slow progress.

    Instead, shifting allocation earlier, to improve origination, without any increase in capital, has an effect equivalent to doubling the total capital pool.

    Industrial Policy via Venture Capital (2025)

    It’s bad for innovation

    Research indicates that origination struggles directly influence which startups are created: Founders who have a hard time finding VCs willing to write their first check end up pivoting to more generic ideas with lower information friction.

    It’s bad for returns

    If all venture returns are downstream of origination, you would expect that a specific focus on origination would lead to outperformance amongst VCs. You would be right:

    “The consensus in recent literature is clear: proactive deal origination is pivotal for achieving superior outcomes in venture capital investments.”

    Where Are the Deals? Private Equity and Venture Capital Funds’ Best Practices in Sourcing New Investments (2010)

    You’re not mad enough about VC incentives

    Fundamentally, this issue will not be resolved as long as the incentives in VC mean the primary opportunity is to maximise fee income by optimising for proxy metrics.

    There is very little intrinsic motivation for VCs to take excessive career risk on highly idiosyncratic ideas, which generate slower markups than consensus startups, in the hope that they may generate some carry a decade down the line.

    In summary: Venture capital is structurally set up to pile capital into categories with low information friction, which is diametrically opposed to innovation.

    You’d have to be brave, crazy or stupid to do anything else.

    The brilliant exceptions

    Fortunately, for everyone involved, there are a few mission-driven firms that have made it their business to focus on origination.

    In today’s market, you’re either a lifecycle capital partner to founders, or you’re a niche operator originating unique opportunities for those who can be.

    To originate deal flow, one needs some combo of:

    – unique networks;
    – top tier reputation in a niche; or
    – uncommon levels of investment rigor for company stage

    All of these help drive signal for the company, which is incredibly valuable in a noisy market.

    Mike Annunziata, Founder and GP at Also Capital

    They have each developed specific proactive strategies to find high potential opportunities, first — sometimes before there’s even a company to invest in.

    • Firms that focus on early conviction and speed, like 1517 Fund and Hustle Fund — who write tiny inception checks to help prospective founders take the first step.
    • Firms that focus on research and expertise, like Compound and Not Boring Capital — who find contrarian needles in consensus haystacks by processing vast quantities of information.
    • Firms that focus on process and scale, like BoxGroup, Boost VC and First Round — who manage the greater idiosyncratic risk of origination with discipline and portfolio strategy.
    • Firms that focus on community and talent density, like South Park Commons, and Entrepreneur First — who allow opportunity to manifest from pools of brilliance.

    (They all share the key elements: community, research, process and speed.)

    It’s hard to state just how much value can be attributed to these firms, and a few others like them. Relative to their size, they are responsible for a disproportionate amount of founder opportunity and downstream potential.

    To understand the potential for these models, Y Combinator and Founders Fund are a good illustration of the same principles at scale. For a range of reasons, these two firms have broken out of the orbit of VC’s structural limitations.

    To conclude, a quote from Danielle Strachman on 1517 Fund’s approach to origination, and some links to great conversations with the other firms above:

    “We call it turning over rocks. It’s like, oh, I went to this campus and I found an interesting young person; we’re turning over rocks. You go to a hackathon and my favorite thing is to look for the young person who is staring off into space. They’re by themselves because they built their own thing. You go up and you talk to them and you’re like, whoa, okay, you are really super nerded-out on security and you’re talking to me like I should know what you’re talking about, and I have no idea. But we’re gonna talk for a while and we’re gonna figure this out.”

    Danielle Strachman, Co-founder and GP at 1517 Fund

    Interviews with the other firms mentioned:

    (top image: “Supersonic”, by Roy Nockolds)

  • The Venture Capitalist’s Paradox

    The Venture Capitalist’s Paradox

    Relying on market efficiency while investing in idiosyncrasy

    Venture capital is the hunt for outliers; ideas that are not well understood by the wider market. This strategy is rooted in the need for risk capital to finance frontier businesses.

    You can see how this played out in previous generations of tech: Amazon, Airbnb, Canva, Coinbase, Dropbox, Google, Shopify, Slack, Uber… All of these companies faced an uphill battle with investor interest, and went on to produce incredible exits for the early believers. Similarly, there are many examples where the founder’s own capital paved the way: SpaceX, Tesla, Palantir, Anduril…

    On the other hand, it seems relatively more difficult to find stories of competitive early rounds leading to great outcomes. Stripe, perhaps?

    This understanding of venture capital is reinforced by the data:

    We find that consensus entrants are less viable, while non-consensus entrants are more likely to prosper. Non-consensus entrepreneurs who buck the trends are most likely to stay in the market, receive funding, and ultimately go public.

    The Non-consensus Entrepreneur: Organizational Responses to Vital Events

    Despite this, today’s venture capitalists have an absurd reliance on the market as their lens to understand value. Herd behavior drives investor attention, and (what passes for) valuation is primarily derived from relative measures like ARR multiples.

    Investors set out to generate alpha with their unique ability to recognise novel opportunities, but rely on broad market sentiment as a lens to understand what is worth pursuing.

    This paradox has stumped observers.

    This heavy reliance on comparable companies in the VC valuation process is perhaps unsurprising, given that relative pricing methods are not uncommon in M&A markets overall. What is less clear, however, is the exact driver behind this method, and the understanding of why a relative pricing methodology will impact startups’ valuations.

    What Drives Startup Valuations?

    Whether it’s marketplaces, crypto or today’s AI boom, capital herds into the category and drives up prices, and those prices then become “comps” for others.

    Ultimately, the surge in deals creates a greater volume of market data for that category, reducing information friction for investment, allowing for more deals to be made more quickly. This compounding influence quickly overheats activity.

    In addition to competition driving up prices and compressing due diligence timelines, there’s a further pernicious consequence: while information friction is reduced around the consensus, it is increased elsewhere.

    Founders building truly innovative products find themselves facing a wall of blank-faced investors programmed with category multiples. The difficulty of raising capital becomes so great that many simply reorient their ambition to lower quality projects closer to the experience of venture capitalists. This is clearly a fundamental failure:

    Information frictions in valuation can lead startups to select projects that align with the expertise of potential venture capital (VC) investors, a strategy I refer to as catering […] where a startup trades off project quality with the informational benefits of catering.

    Startup Catering to Venture Capitalists

    Fundamental Value

    If all of this was to hold true, we should see an increase in performance by the few VCs that maintain a lens on fundamental (rather than relative) value. In theory, these investors would be better able to recognise outlier value and unique opportunities.

    Indeed, that does appear to be the case. Multiple studies on venture capital investment performance and decision making processes have reached the conclusion that VCs would benefit from a better understanding of fundamental value:

    Venture capital funds who base their investment strategy on fundamental values and a long-term view seem to have a measurable advantage over those who engage in subjective short-term trading strategies.”

    How Fundamental are Fundamental Values?

    Ideally, a startup would combine a full fledged fundamental cash flow-based approach with a thorough comparable companies analysis to cover both its intrinsic value and a market-based measure.

    What Drives Startup Valuations?

    So, the paradox is laid bare and the remaining question is why this is the case. There are two potential explanations:

    1. VCs do not understand valuation. A decade of ZIRP-fuelled spreadsheet investing has destroyed the institutional understanding of risk and the purpose of venture capital.
    2. There are other incentives at work which explain this phenomenon; reasons why VCs would be reluctant to closely analyse fundamental value.

    Explanation 1: Hanlon’s Razor

    Unsurprisingly, there’s plenty of evidence to make the case that this is unintentional; a result of simple incompetence and herd behavior. Indeed, herding is a well-studied phenomenon in professional investment, particularly when insecurity is high:

    Under certain circumstances, managers simply mimic the investment decisions of other managers, ignoring substantive private information. Although this behavior is inefficient from a social standpoint, it can be rational from the perspective of managers who are concerned about their reputations in the labor market.

    Herd Behavior and Investment

    Chronic groupthink, and the atrophy of independent reasoning, further explains why VCs are also often unable to clearly articulate the process that goes into their investment decisions:

    The findings suggest that VCs are not good at introspecting about their own decision process. […] This lack of systematic understanding impedes learning. VCs cannot make accurate adjustments to their evaluation process if they do not truly understand it. Therefore, VCs may suffer from a systematic bias that impedes the performance of their investment portfolio.

    A lack of insight: do venture capitalists really understand their own decision process?

    Many VCs have simply emulated the practices of their peers without fully understanding why. Indeed, those peers probably couldn’t provide a rationale either. It’s an industry of investors copying each other’s homework while pretending to be original thinkers.

    Action without understanding purpose naturally erodes standards. Not only does this make VCs bad fiduciaries, it also precludes any learning and institutional development.

    Almost half of the VCs, particularly the early-stage, IT, and smaller VCs, admit to often making gut investment decisions. We also asked respondents whether they quantitatively analyze their past investment decisions and performance. This is very uncommon, with only one out of ten VCs doing so.

    How Do Venture Capitalists Make Decisions?

    Explanation 2: cui bono?

    The alternate theory is that there may be some genuine motive for VCs to avoid looking too carefully at fundamental value. That somehow they are able to profit from a reality in which it is not an important driver of activity.

    Perhaps it is simply because today’s VCs behave more like traders, rather than investors. That the easier opportunity is to glom onto hot categories and ride the exuberance to an overpriced exit somewhere down the line, rather than trying to find good investments.

    This is also not an original accusation:

    For those who are holding on to the belief that venture capitalists are the last bastion of smart money, it is time to let go. While there are a few exceptions, venture capitalists for the most part are traders on steroids, riding the momentum train, and being ridden over by it, when it turns.

    Putting the (Insta)cart before the Grocery (horse): A COVID Favorite’s Reality Check!

    Venture capital, as a discipline, runs an existential risk of invalidating itself by becoming institutionally what crypto is colloquially. If venture capital is just about “[creating] the impression [of] recoupment”, then its no better than the pump and dumps of the crypto bros.

    Institutionalized Belief In The Greater Fool

    Yet again, there’s evidence that this is the case.

    VCs are heavily influenced by market conditions, optimism and FOMO. None of these are original accusations, although it might be interesting to learn this has been demonstrated in research:

    The optimistic market sentiments and fears of missing out in hot markets can significantly shift VCs’ attention towards cheap talk, such as promises of high growth. Such conditions may even prompt VCs to neglect costly signals such as the profitability of new ventures.

    Venture Capitalists’ Decision Making in Hot and Cold Markets: The Effect of Signals and Cheap Talk

    This is confirmed by research looking at this question from the other side, where it is demonstrated that VCs are commensurately less likely to herd in periods with greater uncertainty and less optimistic momentum to channel capital:

    The study finds a significant negative relationship between economic policy uncertainty (EPU) and herding behavior, indicating that venture capitalists are more likely to make independent judgments when EPU rises.

    Economic policy uncertainty and herding behavior in venture capital market: Evidence from China

    Even when a VC talks about wanting to find category winners, they are also implicitly talking about riding a category. Were they hunting for genuine outliers, the category wouldn’t matter. There is a reason, for example, why some VCs widely publicise the categories they invest in as great opportunities, and others choose to keep any alpha for themselves.

    The final reason is simple: subjective, market-based pricing is opaque and open to manipulation. VCs can collectively produce and support higher marks regardless of underlying value. They can also choose to be “opportunistically optimistic” about a portfolio company:

    During fundraising periods the valuations tend to be inflated compared to other periods in the life of the fund. This has large effects on reported interim performance measures that appear in fundraising documents. We find a distinctive pattern of abnormal valuations which matches quite closely the period up to the first close of the follow on fund. It is hard to rationalize the pattern we observe except as a positive bias in valuation during fundraising.

    How Fair are the Valuations of Private Equity Funds?

    Indeed, much of the fallout post-2022 involved LPs feeling fairly miffed that managers weren’t being honest about underlying portfolio company value. As long as VCs broadly maintained marks, there was still hope to raise another fund on those mostly meaningless proxy metrics of performance.

    In Conclusion,

    • Many VCs choose to play a short-term trading game
      By focusing on market momentum, rather than companies, through relative valuation methods, VCs operate more like traders.
    • Most VCs take the path of least resistance when adopting practices
      While analysing fundamental value offers outperformance, relative value is easier to understand and offers strategic advantages.

    Most VCs identify as investors, and some of them still are. Mostly the smaller, boutique firms who were quick to realise that they could not compete in consensus categories against the multi-stage platforms.

    There is value in being a trader if you have multi-billion dollar funds and can both manifest and then coast on the beta of technology markets. They behave like market makers on the way up, extracting opportunistic liquidity, and can aim to concentrate resources into the handfull of winners before the market turns.

    This strategy is toxic to smaller investors, many of whom are simply washed out in the boom-and-bust cycles that this amplifies. Instead, these investors, focused on identifying true outliers, need to consider polishing their lens on fundamental value.

    (top image: Ascending and Descending by M.C. Escher)

  • Explorers and Industrialists

    Explorers and Industrialists

    The two faces of what we sometimes call venture capital, and the cognitive dissonance they create.

    This blog started out as a place to write about the intersection of science fiction and technology. The first article about venture capital, and the opium of consensus, emerged from watching VCs herd into thinly-veiled crypto scams in the name of “web3“.

    The influence of consensus remains poorly understood, and the subject of distracting counterfactuals, despite being widely discussed for as long as “investor” has been a profession.

    Words must have meaning

    Venture capital is the practice of identifying nascent business opportunities with radical potential; the application of process to extract outsized value from extreme idiosyncratic risk.

    In this context, venture capital is clearly not a consensus-oriented discipline. Both theoretical and quantitative perspectives support this reality; the intention, goals, behavior and performance.

    We find that consensus entrants are less viable, while non-consensus entrants are more likely to prosper. Non-consensus entrepreneurs who buck the trends are most likely to stay in the market, receive funding, and ultimately go public.

    The Non-consensus Entrepreneur: Organizational Responses to Vital Events

    Simply look back at the early-days of venture capital’s largest outcomes, where the majority did not have investors competing for access, driving up the price. Fundraising was a struggle for those founders, and in that struggle was the opportunity for those on the other side of the table.

    It’s very hard to make money on successful and consensus. Because if something is already consensus then money will have already flooded in and the profit opportunity is gone. And so by definition in venture capital, if you are doing it right, you are continuously investing in things that are non-consensus at the time of investment.

    Marc Andreessen, a16z

    Indeed, if consensus were to play a meaningful role in venture capital, it would fail on the only two things it sets out to achieve:

    • Maximise ROI for LPs through idiosyncratic risk
    • Finance the development of novel innovations

    In addition, there is no such thing as a downstream supply of “non-consensus capital”. If you fund non-consensus companies then you have to be able to support them to the point where their potential is obvious and larger/later generalists can be convinced. It’s paradoxical to believe that other investors will share your non-consensus viewpoint.

    Cognitive dissonance

    The root of the confusion about consensus (and entry price, portfolio construction, attention, relationships…) is the mixing of two different private market strategies. One is venture capital, and the other is something else that just falls into the venture capital allocation bucket.

    This other strategy emerged in the period from 2011 to 2021, enabled by low interest-rates, as described by Everett Randle in “Playing different games“:

    Tiger identified several rules / norms / commonly held ideas in venture/growth that are stale & outdated and built a strategy to exploit the contemporary realities around those ideas at scale.

    Everett Randle, Kleiner Perkins

    The capital mechanics of this strategy were explained further by Kyle Harrison, in “The Unholy Trininty of Venture Capital“:

    So you have massive capital allocators looking for places they can farm yield and they don’t want to be slinging hundreds of $30M checks. Capital agglomerators represent the perfect solution. Hit your 7-8% yield target, be able to park $250M a pop without being the majority of the fund, and sit back and relax.

    Kyle Harrison, Contrary

    Versions of “bigger/faster/cheaper capital” have since been employed by other multi-stage platform firms, and the consquences are dramatic:

    If success in venture capital is driven by non-consensus investments, in less competitive ecosystems with more rational pricing, why would an investor pursue a strategy directly to the contrary?

    The answer is indicated in Martin Casado’s episode with Harry Stebbings, in which he described missing the category winner as the greatest sin of investing.

    This hunger to capture the most extreme “power law” category leaders is a requirement of the exit math involved in multi-billion dollar funds. Consequently, these platforms also raise substantial early-stage funds to index any emerging theme, putting an option on the future of those companies.

    A mega-VC with $5-10B annual funds is really searching for only one thing: a company they can pile over $1b into with a potential for 5-10X on the $1b. With this, seed fund is inconsequential money used to increase the odds of main objective.

    Bill Gurley, Benchmark

    The startup industrial complex that has emerged is not optimised for non-consensus investing, and nor does it need to be. Investors at these platforms are hired to compete and win in known areas — and have attitudes to match:

    Successful startups fit into a mold that investors understand, and that more often than not those startups attracted meaningful competition among top investors.

    Martin Casado, a16z

    If a company has tons of hype and seems overvalued, don’t run away. Run towards it. Hype is good. Means they’ll raise, exit at higher valuation. And the price likely won’t feel overpriced after the startup exits.

    Andrew Chen, a16z

    The output is a rough index of high-growth private technology companies. The platforms are harvesting the beta from innovation, rather than finding the alpha in outliers. Even the giant outcomes become so well/over-priced that their returns risk converging with benchmarks.

    Categorically, this is not venture capital in any meaningful sense.

    The only reason we call this venture is because LPs need to call it venture so CIOs can hit annual allocation targets they promised boards. This is venture allocation, not venture returns.

    Will Quist, Slow

    Venture Alpha and Venture Beta

    To repeat a point already well-hammered, the platform strategy is entirely different, with a different LP base, a different return profile, and different rules.

    The difference between the Andreessen quote above, and the more recent quotes from Chen and Casado, is simply that in 2014 Andreessen Horowitz was a venture capital firm. Today it is an asset manager, an RIA with a multi-stage platform strategy, perhaps best described as a venture bank.

    Many VCs have sought to assimilate “tier 1” multi-stage behavior, acting out what they believe LPs and peers expect to see despite the fundamentally incompatible models. This herding around identity and behavior reflects the extreme level of insecurity in venture capital, a product of the long feedback cycles and futility of trying to reproduce success in a world of exceptions.

    Venture Banks

    There is no harmony with venture capital, and the behaviors of these platform investors should not be emulated by venture capitalists — whether or not they also call themselves venture capitalists.

    To put a point on this: The platforms explicitly benefit from consensus and price inflation. Both are toxic to venture capital.

    As long as both strategies are discussed under the banner of venture capital, we’ll keep wasting time on pointless debates about markets and incentives, and investors will keep making dumb, confused decisions.

    (top image: A Steam Hammer at Work, by James Nasmyth)

  • The IPO Decision

    The IPO Decision

    The influence of productivity shocks, peer effects and cost of capital on AI IPO ambitions, and what happens next.

    While leaders at xAI, Anthropic and Mistral have been silent on their plans to go public, OpenAI is starting to open up.

    Back in May it was reported that negotiations with Microsoft included provisions that allowed OpenAI to file for an IPO. The transition to a Public Benefit Corporation (PBC) the following month made that technically possible. Both Altman (CEO) and Friar (CFO) have made statements alluding to the process since. Indeed, simply the fact that Friar is being put in front of the media more often as a leadership figure is a significant signal.

    OpenAI’s most recent release may underline this direction. By prioritising model economics (focusing on the “router” capability) rather than model performance, the reception to GPT-5 was poor. In reality, this may reflect a shift in posture toward public market metrics, and their willingness to take the PR hit.

    The prompt router also lays the groundwork for OpenAI to provide selective access to more expensive models. The next generation of LLMs will be powered by NVIDIA’s Blackwell chips, offering ~30x faster real-time inference. The chips are rolling out at the moment, with an impact on model releases expected next year.

    Assuming these models will be a major step-up in competence, this could be the tipping point for a wave of AI IPOs in 2026.


    Factor 1: Productivity Shocks

    In our model, two firms, with differing productivity levels, compete in an industry with a significant probability of a positive productivity shock. Going public, though costly, not only allows a firm to raise external capital cheaply, but also enables it to grab market share from its private competitors.

    IPO Waves, Product Market Competition, And the Going Public Decision: Theory and Evidence

    When an industry experiences (or anticipates) a significant positive productivity shock (an inflection point in their ability to generate value), this may trigger an “IPO wave”.

    Essentially, if there’s a significant step-up across the industry then there’s a real incentive to be the first (or at least be early) to tap public markets for capital to drive market-share expansion.

    LLMs have continued to improve over the last few years, with a number of hyped releases and growing experimentation amongst enterprise users, but there has yet to be a truly significant “productivity shock” moment.


    Factor 2: Peer Effects

    We find that observing a peer go public within the previous 12 months raises the propensity to undertake an IPO from a baseline rate of 0.31 percent per quarter to 0.44 percent per quarter, amounting to a 40 percent increase in IPO propensity. This result is robust to accounting for hot market effects and other common shocks that may affect competing firms’ IPO decisions.

    IPO Peer Effects

    The first to market has an advantage in that they may capture the demand for that industry amongst public market investors. They also bear all of the cost and the risk of blazing that trail, primarily that they might have greatly overestimated demand.

    There is some benefit to being a “fast follower” in these circumstances, which is often what triggers the “IPO wave” dynamic seen in the culmination of tech cycles. However, the later you are in that wave, the less of the benefit you capture.

    These periods, often characterised as “IPO windows” have been referred to in literature as “windows of misopportunity” for investors due to the increased failure rate. However, it’s also true that the few survivors tend to appear more innovative (in patent quality and quantity) than IPOs issued in other periods.

    Overall, this chapter tend to conclude that “windows of opportunity” provides real opportunity to the most inventive private firms and allow them to raise public capitals to further their innovations.

    Essays On Ipo Cycles And Windows Of Opportunity

    Factor 3: Cost of Capital

    We find that less profitable companies with higher investment needs are more likely to IPO. After going public, these firms increase their investments in both tangible and intangible assets relative to comparable firms that remain private. Importantly, they finance this increased investment not just through equity but also by raising more debt capital and expanding the number of banks they borrow from, suggesting the IPO facilitates their overall ability to raise funds.

    Access to Capital and the IPO Decision: An Analysis of US Private Firms

    There’s a common perception that going public is for mature companies who are past the period of aggressive growth, looking for more stable access to capital. This does not appear to be true.

    In fact, companies that IPO are often doing so in order to increase their investment in growth, including intangible assets including R&D spend. This is particularly true in heavily competitive markets and capital-intensive businesses.

    This has obvious relevance to LLM providers, who check a lot of these boxes. Certainly, in the phase of investing in infrastructure to support scale, lowering the cost of capital is a major priority.


    Factor 4: Beyond Hedging

    Similar to going public, hedging mitigates the effect of risk on a firm’s product market strategy, and, thus, results in greater product market aggressiveness. Therefore, in the presence of product market competition, hedging has a strategic benefit similar to that of an IPO. Importantly, we show that the availability of hedging reduces, but does not eliminate, the incentives to go public.

    Strategic IPOs and Product Market Competition

    Not necessarily a reason why LMM providers may look to IPO, but rather why they haven’t until now: “Hedging” in this context effectively reflects the relationships that many model providers have with large public companies like Microsoft, Amazon or Apple.

    Rather than going public themselves, they can rely on these partnerships to fund investment and distribute risk, offering some of the benefits of going public without any of the costs.

    However, the example of OpenAI’s relationship with Microsoft illustrates that it’s possible to outgrow these arrangements.


    IPO Windows

    Generally speaking, “IPO windows” are a mirage chased by liquidity-starved venture capitalists. A truly great company, like Figma, can IPO more-or-less whenever it wants to.

    However, that dynamic changes when you have a group of peer-companies in a fiercely competitive (and capital intensive) industry. At that point, it is likely that there will be some strategic clustering of IPO ambitions.

    A true “IPO window”, 1999/2000 or 2021, involves ~1,000 companies listing in the space of about six months. Diligence collapses, the quality of companies goes in the toilet, and public markets are torched for years afterwards. Sarbanes-Oxley killed this behavior in 2002, and it didn’t appear again until the low-interest-rate pandemic briefly drove public markets insane in 2021.

    Why Wait

    Assume that OpenAI is likely to be the first out. As today’s AI leader, with the widest consumer adoption and biggest brand, it seems the best positioned.1

    What are they waiting for?

    Primarily, they’ll be waiting to see if Blackwell unlocks the kind of productivity shock they are looking for. To clear their recent $500B valuation they’ll need to go public with undeniable momentum and a great story to tell new investors about future potential.

    Secondly, going public is just a huge amount of work. Both in a technical sense, preparing the company’s books for intense scrutiny, and in a brand and PR sense. Prospective investors may need educating about the product, or the image of leadership may need some rehabilitation.2

    IPOs are remarkably intense, and represent the most thorough inspection that a company will endure in its lifetime. This is why companies and their board of directors agonize over whether or not they are “ready” to go public. Auditors, bankers, three different sets of lawyers, and let us not forget the S.E.C., spend months and months making sure that every single number is correct, important risks are identified, the accounting is all buttoned up, and the proper controls are in place.

    Investors Beware: Today’s $100M+ Late-stage Private Rounds Are Very Different from an IPO

    Where Bubbles Emerge

    There has been endless talk of a bubble of AI investment, and certainly there seems to be a disconnect between price and value.

    This is true in private markets, reflected in transaction data, and in public markets, reflected by the delta between the MAG7 (all somewhat AI-connected) and the other 497 companies in the S&P.

    However, the truth is that bubbles only really happen in public markets. They require liquidity, enabling the wild sentiment-driven swings in price that characterise a bubble.

    In illiquid markets, like venture capital, you have what William Janeway called “speculative episodes”, which may be derived from a bubble playing out in public markets (via comps) but do not behave in the manner of a bubble.

    It’s almost as if wherever there is a liquid trading secondary market in assets, there you will find a bubble.

    The Upside of Wasteful Speculative Bubbles and the Downside of Efficiency

    Indeed, the concept of bubbles has been used in VC to disguise what is better described as simple greed and myopia. Investors behaving like traders — “riding the momentum train, and being ridden over by it, when it turns” — to quote Damodaran.

    It’s illogical to describe what is happening today as a bubble if all of the current participants (including Altman himself) acknowledge that it looks like a bubble. A key feature of speculative bubbles is surely that the participants do not realise it’s a bubble? A more honest characterisation is simply that VCs are choosing to gamble on AI because their LPs believe they should.

    This all changes when AI companies hit public markets, and the pool of investors (and capital) grows dramatically.

    Consider the environment: post productivity shock, with an IPO wave led by the largest model providers but cascading into related industries and any company tha can crest the narrative.

    This is precisely, and clasically, when we’d see a bubble emerge; in the volatile public markets, rather than the sluggish and opaque private markets.3

    Until then, call it what it is: degenerate trading behavior.


    (top image: Allegory on Tulipmania by Jan Brueghel the Younger)

    1. Arguably, xAI is the second in-line. [↩]
    2. As a minor footnote here, I believe Altman’s recent comments about AI as a bubble, his uncertainty at leading a public company, and an AI CEO in 3 years, are all deliberate narrative prompts. [↩]
    3. This also fits neatly with Howard Mark’s comments about the markets feeling ‘expensive’, and the potential for a major correction in the not-so-distant future. [↩]